

How to Prepare Financial Statements for Loan Applications
You may think you’re ready for a loan, but here’s the hard truth: lenders don’t just hand out money because your business is “doing okay.”
They want proof — solid, organized, crystal-clear financial proof that shows you can pay them back, grow your business, and stay stable through ups and downs.
That proof lives in your financial statements.
But most small business owners have no idea what lenders actually look for when they say, “Send over your financials.” Even fewer know how to prepare those documents in a way that makes SBA 504 lenders say, “This is someone we can trust.”
This guide breaks down the full process of preparing your financial statements for an SBA 504 loan, especially if you’re working with a Certified Development Company (CDC) like 504 Capital Corporation.
Whether you’re just starting your application or you’ve already spoken with an SBA 504 lender, this walkthrough is your roadmap. You’ll know exactly:
- What to prepare
- How to organize it
- What lenders care about (and what they don’t)
- How to keep the SBA CDC loan process moving smoothly
- What kind of post-loan support you can expect
Let’s make your numbers tell the story lenders want to hear.
Table of Contents
Start with a Certified Development Company (CDC)
If you’ve never worked with one before, a Certified Development Company (CDC) is a nonprofit organization authorized by the SBA to support small business borrowers through the SBA 504 loan process.
What does a Certified Development Company do
They:
- Guide you through the paperwork
- Help structure your financing
- Work directly with SBA 504 lenders and banks
- Stay with you post-loan for support
Unlike traditional banks, a CDC doesn’t just hand you forms and send you off. They coach you through the process — making sure your application is accurate, compliant, and well-structured.
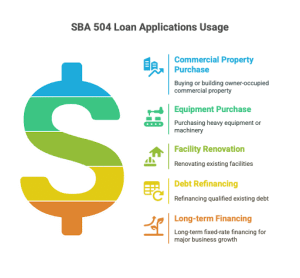
1. Initial Consultation & Needs Assessment: Start Smart with a Certified Development Company
Before we even talk about financial statements, you need to understand your loan goals — and that’s where your first conversation with a Certified Development Company (CDC) comes in.
During the initial consultation, your CDC partner (like 504 Capital Corporation) will:
- Assess your business goals: Are you buying commercial property? Upgrading equipment?
- Explain how the SBA CDC 504 loan structure works
- Determine the funding amount and repayment terms that best fit your situation
- Walk you through what financial documents will be required
Why This Step Matters
Jumping into loan paperwork without this clarity leads to wasted time, frustration, and rework. The CDC isn’t just a lender — they’re your guide through the process. They’ll also help you avoid common mistakes that slow down (or completely derail) SBA loans.
Want to go deeper into how the CDC 504 program works? Check out the CDC/504 Certified Development Company Loan Program.
2. Gathering Financial Documentation: What Lenders Want — and Why
Now comes the meat of it: preparing the financial statements that will anchor your entire loan application.
Here are the essential financial documents you’ll need — and what lenders are looking for in each:
Balance Sheet
Shows what your business owns and owes at a specific moment.
Lenders use it to measure your:
- Assets vs. liabilities
- Business health
- Liquidity (Can you cover your debts?)
Tip: Make sure it’s recent — ideally within 90 days. Outdated sheets = red flag.
Income Statement (Profit & Loss)
Tracks revenue, expenses, and net income over time. Lenders look for:
- Consistent profitability
- Expense control
- Revenue trends
Tip: Include both year-to-date and past 2–3 years for context.
Cash Flow Statement
Shows the actual flow of cash — not just profits — in and out of your business.
Lenders want to know:
- Can you make your loan payments from real cash flow?
- Are you overextended?
Tip: Many businesses show profit but are cash poor. Cash flow matters more for loans.
Business Tax Returns (Last 3 Years)
Verifies the numbers you’ve reported — and shows your business’s financial integrity.
Tip: If your tax returns don’t match your P&L, you’ll need to explain why.
3. Application Support: Organizing Financials the Right Way
Once you’ve gathered the documents, don’t just attach them to an email and hope for the best.
Presentation matters. Lenders don’t want to hunt for numbers. They want a clean, easy-to-follow financial package.
Here’s how to format it for clarity:
- Label each document with the business name and date range
- Keep everything in PDF format
- Create a one-page “financial summary” upfront: total revenue, net income, total assets, etc.
- If possible, have a CPA review your numbers
If you’re working with a CDC, they can help review these documents before submission. That’s one of the advantages of working with a certified development company — they’re in your corner from the start.
4. Structuring the Loan: Know What You’re Getting Into
The SBA 504 loan isn’t like a traditional loan. It’s structured in a way that reduces your down payment, lowers risk, and still gets you the capital you need.
Here’s the typical setup:
- Bank: 50% of the loan amount
- CDC (like 504 Capital): 40%
- You (the borrower): 10% equity injection
So if your project costs totals $1 million:
- Bank lends $500,000
- CDC provides $400,000
- You contribute $100,000
This setup lowers your monthly payments and gives you longer repayment terms—up to 25 years—with a low fixed interest rate. That’s why SBA 504 financing is a go-to tool for smart business owners.
Want more technical details? Visit 504 Capital Corporation for the full breakdown.
5. Communication Throughout the Process Is Everything: Stay Active in the Process
Here’s the part many business owners underestimate: the power of clear, consistent communication.
You might have perfect financials and a rock-solid business model. But if you’re unresponsive or vague during the application SBA CDC loan process, lenders can lose confidence.
Here’s what “good communication” looks like:
- Respond to document requests within 24–48 hours
- Ask questions if anything’s unclear
- Proactively share updates if your financials change
- Schedule weekly check-ins with your CDC advisor
Remember: your CDC is your partner, not just a processor. Keeping things moving is a shared job.
6. Post-Funding Support: What Happens After the Loan Is Approved?
Getting the funds isn’t the finish line—it’s just the next chapter.
The best CDCs (like 504 Capital) continue to support you after the loan closes. Here’s what that might include:
- Help with financial reporting for compliance
- Guidance on using funds efficiently
- Support for refinancing if needed in the future
- Strategic advice for your next stage of growth
This is where a relationship with your CDC loan assistance really matters. You’re not just a transaction—you’re a long-term investment.
Want to Stop Guessing and Start Growing? Here’s Your First Step.
Let’s face it—applying for a loan is stressful. You’re asked for documents you barely understand, acronyms fly around like confetti, and you’re afraid that one small error could get you denied.
But with the right guidance, it becomes manageable. With a certified development company, it becomes an opportunity to strengthen your business—not just get funding.
Whether you’re preparing your first application or you’re tired of getting stuck in loops with traditional lenders, we’re here to help you win.
504 Capital Corporation is a trusted CDC and one of the top-performing SBA 504 lenders in the region. We work under the ALP (Accredited Lender Program), which means we can speed up the approval process for you. Our experts in SBA 504 financing guide you through everything — from financial prep to post-loan support.
At 504 Capital Corporation, we proudly support businesses across Virginia, North Carolina, and Maryland, and DC. Whether you’re expanding your warehouse in Richmond, buying new equipment in Raleigh, or investing in real estate in Baltimore — we’re ready.
Contact us today, and let’s take the guesswork out of your loan application.